Owning a home in Toronto is a significant financial commitment, and managing a mortgage effectively is an important part of long-term financial planning. As interest rates, household expenses, and personal circumstances change, homeowners may consider refinancing their existing mortgage to improve cash flow, consolidate debt, or access accumulated home equity. However, refinancing is not automatically the best financial decision for everyone. Understanding the process, associated costs, and potential benefits can help homeowners determine whether restructuring their mortgage aligns with their financial goals.
For homeowners exploring Home mortgage Refinance in Toronto, understanding both the financial and legal aspects of the process is essential. Mortgage refinancing typically involves replacing an existing mortgage with a new loan agreement, potentially featuring different interest rates, repayment terms, or borrowing amounts. Since refinancing affects property ownership obligations and long-term financial commitments, careful planning and professional guidance can help reduce unexpected complications.
What Is Home Mortgage Refinancing?
Mortgage refinancing is the process of replacing an existing mortgage with a new mortgage agreement. The new financing may be arranged through the current lender or a different financial institution.
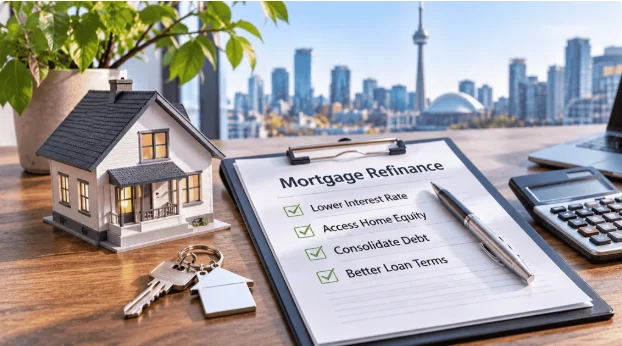
Homeowners refinance for several reasons, including obtaining a more competitive interest rate, changing their mortgage structure, accessing home equity, or consolidating existing debts.
Unlike a standard mortgage renewal, refinancing may involve changing the outstanding loan amount or other significant borrowing terms.
How Does Mortgage Refinancing Work?
The refinancing process generally begins with an assessment of the homeowner’s financial situation and current mortgage conditions.
Lenders typically evaluate income, credit history, outstanding debts, property value, and the amount of equity available in the home.
If approved, the new mortgage funds are used to discharge the existing mortgage, with any additional approved funds distributed according to the refinancing arrangement.
The homeowner then begins making payments under the new mortgage terms.
Why Toronto Homeowners Consider Mortgage Refinancing
Toronto’s housing market and changing borrowing conditions can influence homeowners’ refinancing decisions.
Although individual circumstances vary, several common financial objectives encourage property owners to explore their options.
1. Securing a More Competitive Interest Rate
One common reason for refinancing is the possibility of obtaining a lower mortgage interest rate.
A reduced rate may lower monthly payments or decrease the total interest paid over the remaining mortgage period.
However, homeowners should compare potential savings against mortgage discharge fees, prepayment penalties, legal expenses, and other refinancing costs.
A lower advertised rate does not necessarily mean refinancing will produce overall savings.
2. Consolidating High-Interest Debt
Some homeowners refinance to combine outstanding debts into a single mortgage.
Credit cards, personal loans, and other unsecured debts often carry higher interest rates than residential mortgages.
Consolidating these balances may simplify repayment and reduce immediate monthly obligations.
However, extending short-term debt over a longer mortgage amortization period can increase total interest costs.
It also converts unsecured debt into debt secured against the home, potentially increasing the consequences of missed payments.
3. Accessing Home Equity
Home equity represents the difference between a property’s current market value and the outstanding debt secured against it.
For example, if a property is valued at $900,000 and the remaining mortgage balance is $500,000, the homeowner has approximately $400,000 in equity before accounting for other secured obligations and transaction costs.
However, this does not mean the entire equity amount is available for refinancing.
In Canada, conventional mortgage refinancing is generally limited to 80% of a property’s appraised value, subject to lender approval and applicable rules.
Homeowners may use eligible equity for renovations, education expenses, investments, or other financial priorities.
Understanding Mortgage Refinancing Costs in Toronto
Before proceeding with refinancing, homeowners should understand the expenses involved.
These costs can significantly influence whether refinancing makes financial sense.
Mortgage Prepayment Penalties
Breaking a closed mortgage before the end of its term may result in a prepayment penalty.
For fixed-rate mortgages, the penalty may be calculated using an interest rate differential or a specified number of months’ interest, depending on the mortgage agreement.
Variable-rate mortgages may have different penalty structures.
Homeowners should request a written payout statement from their lender before making a refinancing decision.
Legal Fees and Registration Expenses
Mortgage refinancing often requires legal work to discharge the existing mortgage and register the new mortgage against the property.
Legal professionals may also review lender instructions, verify ownership details, and identify registered interests affecting the property.
Additional expenses may include title-related charges, registration fees, and other disbursements.
Property Appraisal Fees
Lenders may require a property appraisal to establish the home’s current market value.
The appraisal helps determine the amount of financing available and whether the property meets the lender’s requirements.
In some situations, lenders may use alternative valuation methods, but a formal appraisal may still be necessary.
The Role of Real Estate Lawyers in Mortgage Refinancing
Mortgage refinancing is not solely a financial transaction. It also involves legal obligations related to property ownership, lender security, and registered interests.
A real estate lawyer can help homeowners understand the legal documentation and complete the required registration procedures.
Firms such as Affinity Law provide legal services relevant to real estate transactions. When selecting legal representation, homeowners should consider experience with Ontario mortgage refinancing, communication practices, and the scope of services provided.
Reviewing Mortgage Documents
A lawyer may review the new mortgage instructions and supporting documents to ensure the transaction is completed according to the lender’s requirements.
This process can help identify issues involving registered ownership, existing mortgages, or other interests affecting the property.
Discharging the Existing Mortgage
When refinancing with a different lender, the existing mortgage generally needs to be paid out and discharged.
The lawyer coordinates the required documentation and registration steps to complete the transaction.
Addressing Title and Registration Issues
Property title searches can reveal registered mortgages, liens, or other interests that may need to be addressed before refinancing proceeds.
Identifying these issues early can help prevent closing delays and unexpected expenses.
How to Decide Whether Refinancing Makes Financial Sense
Refinancing should be evaluated using more than the monthly payment amount.
Homeowners should calculate their total borrowing costs and consider how the new mortgage affects long-term financial security.
Compare Total Interest Costs
A lower monthly payment may seem attractive, but extending the amortization period can increase the total interest paid.
For example, refinancing a mortgage with 15 years remaining into a new 25-year amortization schedule may reduce monthly payments while increasing the overall cost of borrowing.
Comparing repayment schedules can help homeowners understand the financial trade-offs.
Calculate the Break-Even Point
The break-even point estimates how long it takes for refinancing savings to recover the upfront costs.
Suppose refinancing costs $4,000 and produces monthly savings of $200.
The approximate break-even period would be:
$4,000 ÷ $200 = 20 months.
This simplified calculation assumes the monthly savings represent genuine financial savings rather than merely extending the repayment period.
Homeowners should also account for changes in total interest, mortgage terms, and potential future penalties.
Consider Long-Term Financial Goals
Refinancing decisions should reflect broader household priorities.
Some homeowners want to reduce monthly expenses, while others prioritize paying off their mortgage faster.
Those considering renovations, retirement planning, or additional property investments should evaluate how refinancing affects available cash and future financial flexibility.
For broader financial planning, homeowners can also explore key factors that influence real estate investment decisions, including borrowing costs, property values, and long-term financial risk.
Mean Texting
Common Mortgage Refinancing Mistakes to Avoid
Even experienced homeowners can make costly mistakes when refinancing.
Focusing Only on the Interest Rate
Interest rates are important, but they represent only one part of the borrowing arrangement.
Mortgage penalties, lender fees, repayment flexibility, and amortization periods can substantially affect the total cost.
Borrowing More Than Necessary
Accessing home equity can provide financial flexibility, but additional borrowing increases the amount secured against the property.
Homeowners should establish a clear purpose for the funds and evaluate whether the additional debt is affordable.
Ignoring Mortgage Contract Restrictions
Some mortgages contain restrictions involving prepayments, transfers, portability, or early termination.
Reviewing these conditions before applying for refinancing can help prevent unexpected expenses.
Failing to Compare Lenders
Different lenders may offer varying rates, qualification requirements, repayment options, and fees.
Comparing multiple offers can help homeowners identify financing arrangements that better match their financial circumstances.
When Is the Best Time to Refinance a Mortgage in Toronto?
There is no universally ideal time to refinance.
The decision depends on mortgage terms, current borrowing costs, property equity, and personal financial objectives.
Homeowners approaching their mortgage renewal date may find refinancing more convenient because they can potentially avoid penalties associated with breaking an existing closed mortgage.
Others may consider refinancing earlier when the expected financial benefits justify the additional expenses.
Changes in household income, property value, or financial priorities can also influence the decision.
Before proceeding, homeowners should review their current mortgage agreement, request an accurate payout statement, and compare available financing options.
Conclusion
Home mortgage refinancing in Toronto can provide opportunities to restructure debt, access property equity, or adjust monthly payments. However, these potential advantages should be weighed against legal expenses, mortgage penalties, interest costs, and long-term financial obligations.
Understanding the refinancing process allows homeowners to make decisions based on their actual financial needs rather than short-term payment reductions.
By comparing lenders, evaluating total borrowing costs, and obtaining appropriate legal and financial guidance, Toronto homeowners can approach mortgage refinancing with greater confidence.
A carefully planned refinancing strategy can support financial flexibility while helping homeowners maintain a sustainable approach to managing their property and long-term debt.
Disclaimer: This article is intended for general informational purposes only and does not constitute legal, mortgage, or financial advice. Lending requirements and applicable regulations may change. Homeowners should consult qualified Ontario professionals before making refinancing decisions.
Read More: Understanding the Key Factors That Influence Real Estate Investment Decisions